
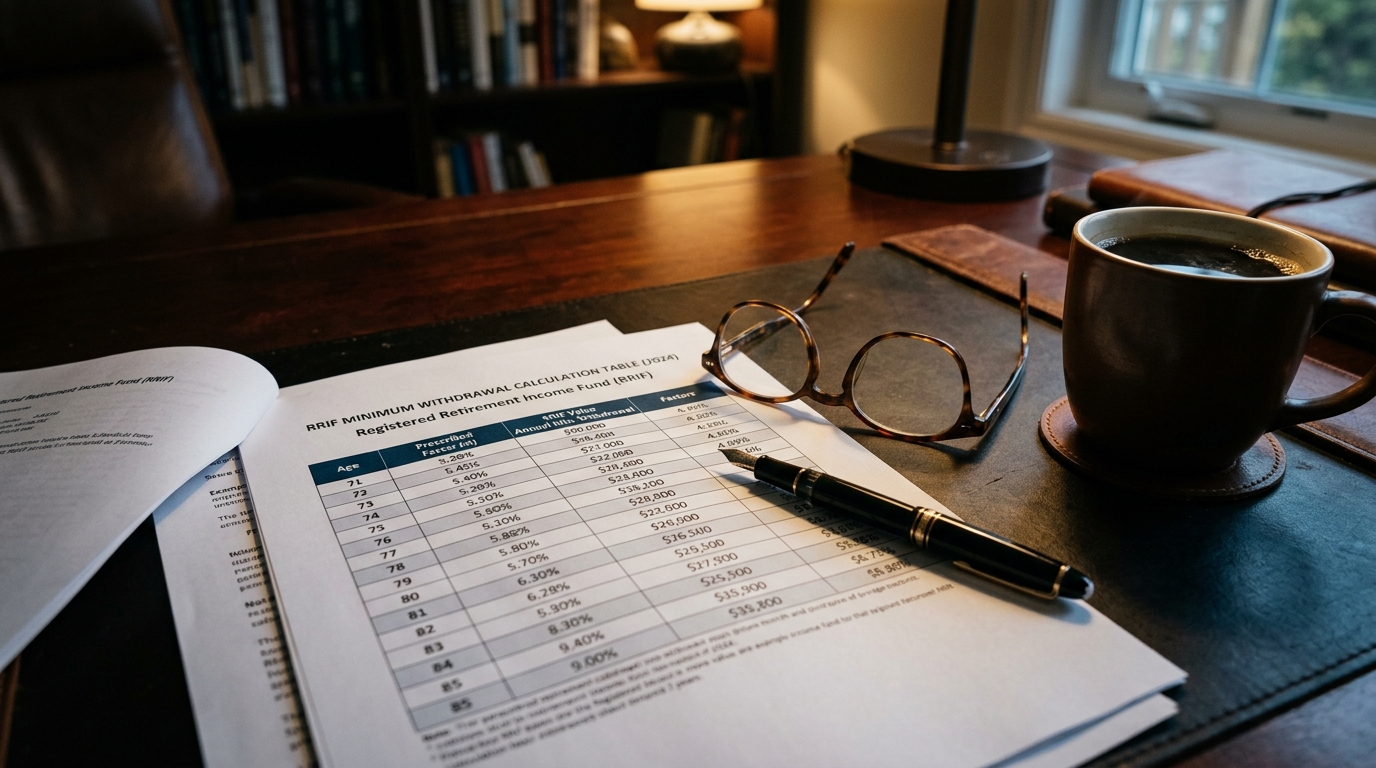
For more than four decades of an investor’s career, registered retirement savings operate on pure accumulation: tax-deductible contributions, automated compound interest, and delayed tax liabilities. But the moment a Canadian reaches age 71, the Canada Revenue Agency transforms from an accommodating savings partner into an aggressive tax collector. Under the federal Income Tax Act, the accumulation phase terminates permanently, and the mandatory de-accumulation engine of the Registered Retirement Income Fund (RRIF) takes command.
- The Age 71 Hard Deadline: All RRSPs must be liquidated, converted to a RRIF, or used to purchase an annuity by December 31 of the year you turn 71. Failing to convert triggers full deemed liquidation of your entire account balance as ordinary income in a single tax year.
- The Statutory Percentage Curve: Prescribed annual minimum withdrawals start at 5.28% at age 71, reaching 8.51% at age 88, and capping at 20.00% at age 95.
- The Spousal Age Elective Shield: Electing to base your RRIF minimums on a younger spouse’s birthdate permanently reduces mandatory taxable distributions, dramatically reducing Old Age Security (OAS) recovery tax clawbacks.
- Cross-Referenced Retirement Forensics: Coordinate these rules with our investigations on executing a strategic RRSP meltdown before age 71 and our analysis of the CPP & OAS delay optimization framework.
The Complete Canadian RRIF Minimum Withdrawal Schedule (2026)
Your annual RRIF minimum withdrawal is calculated by multiplying the market value of your RRIF on January 1 of each calendar year by the CRA’s prescribed statutory percentage for your age. At age 71, the factor is 5.28%; at age 75, it is 5.82%; at age 80, it is 6.82%; and at age 95+, it reaches 20.00%.
The annual mandatory minimum withdrawal is legally defined under Subsection 146.3(1) of the Income Tax Act. The government’s objective is to systematically deplete tax-sheltered accounts throughout a retiree’s lifetime so that accumulated earnings are fully subjected to progressive marginal tax rates before estate settlement.
| Age on January 1 | CRA Prescribed Factor (%) | Mandatory Minimum on $500,000 Portfolio | Mandatory Minimum on $1,000,000 Portfolio | Mandatory Tax Withholding |
|---|---|---|---|---|
| Age 71 | 5.28% | $26,400 | $52,800 | 0% (Zero Withholding) |
| Age 72 | 5.40% | $27,000 | $54,000 | 0% (Zero Withholding) |
| Age 75 | 5.82% | $29,100 | $58,200 | 0% (Zero Withholding) |
| Age 80 | 6.82% | $34,100 | $68,200 | 0% (Zero Withholding) |
| Age 85 | 8.51% | $42,550 | $85,100 | 0% (Zero Withholding) |
| Age 90 | 11.92% | $59,600 | $119,200 | 0% (Zero Withholding) |
| Age 95+ | 20.00% | $100,000 | $200,000 | 0% (Zero Withholding) |
The Spousal Age Optimization Strategy: How to Slash Minimum Withdrawals
When establishing a RRIF, Subsection 146.3(1) allows you to elect your younger spouse’s age to set your mandatory withdrawal percentage. This election must be made before your first withdrawal, is permanent, and allows retirees with outside wealth to minimize taxable distributions, leaving capital compounding tax-sheltered longer.
Consider a 71-year-old retiree with a $1,000,000 RRIF whose spouse is 64 years old. Under standard rules using their own age, their age 71 withdrawal factor is 5.28%, forcing a mandatory distribution of $52,800. However, if they elect to base the RRIF on their 64-year-old spouse, the pre-age-71 formula applies: 1 / (90 - Spouse Age). For a 64-year-old spouse, the factor is 1 / (90 - 64) = 1 / 26 = 3.85%.
Basing the account on the younger spouse slashes the mandatory taxable withdrawal to $38,500—immediately shielding $14,300 from high marginal tax brackets in year one alone. For retirees whose pensions, corporate dividends, and rental incomes already push them close to the Old Age Security clawback threshold ($93,208+), this single election can save thousands of dollars per year in avoided OAS recovery tax.
RRIF Tax Withholding Rules: The Excess Withdrawal Trap
The CRA does not mandate tax withholding on the statutory minimum RRIF amount. However, any sum withdrawn beyond the minimum is subject to immediate mandatory withholding: 10% on excess amounts up to $5,000, 20% on excess amounts up to $15,000, and 30% on amounts exceeding $15,000.
Retirees often mistakenly assume that because no tax was withheld from their statutory minimum distribution, the withdrawal is tax-free. It is not. All RRIF distributions are taxed at your full marginal personal income tax rate. If your financial institution withholds 0% throughout the year, you may face a massive, unexpected tax bill when filing your annual T1 tax return, along with mandatory CRA quarterly tax installment requirements.
The RRIF conversion deadline at age 71 is the ultimate structural tax reckoning in Canadian personal finance. Waiting passively until December of your 71st year to confront a seven-figure RRSP invites brutal marginal tax brackets and guaranteed OAS clawbacks. Sophisticated wealth preservation requires proactive planning: execute disciplined, strategic RRSP meltdowns between ages 60 and 70 to fill low marginal tax brackets, and if you have a younger spouse, ensure you lock in the spousal age election the moment the RRIF is formed to retain absolute control over your taxable income stream.
People Also Ask
Can you change the RRIF spousal age election after opening the account?
No. The election to base your RRIF minimum withdrawals on your spouse’s age must be made on the initial application form before your very first withdrawal is executed. Once established, the election cannot be altered, even in the event of divorce or the death of the spouse.
What is the $2,000 Pension Income Tax Credit for RRIFs?
Once you reach age 65, eligible RRIF withdrawals qualify for the federal Pension Income Tax Credit. This allows retirees to claim a federal non-refundable tax credit of 15% on the first $2,000 of eligible pension income, effectively allowing $2,000 in annual RRIF withdrawals to be received completely tax-free at the federal level.
Can you transfer unused RRIF withdrawals into a TFSA?
You cannot transfer funds directly from a RRIF to a TFSA on a pre-tax basis. However, if you do not require your mandatory RRIF withdrawal for daily living expenses, you should withdraw the net funds after tax and immediately deposit them into your TFSA (subject to available contribution room) where future growth and withdrawals will remain 100% tax-free.
What happens to a RRIF upon death in Canada?
If you designate your spouse as a “successor annuitant,” the RRIF transfers directly to them with zero deemed disposition or tax liability, and they continue receiving distributions. If no qualified beneficiary is designated, the entire fair market value of the RRIF is included as taxable income on the deceased’s final terminal tax return, often triggering a catastrophic 53.5% top marginal tax hit.
Related Investigations: Explore LIF Withdrawal Rules & 50% Unlocking in Canada and our analysis of the Canadian Dividend Tax Credit Trap for Retirees.